Key takeaways
- Since 1 January 2025, all domestic businesses in Germany have had to be able to receive e-invoices in B2B transactions.
- From 1 January 2027, companies with prior-year turnover above €800,000 must issue e-invoices, and from 2028 all other companies must too.
- A simple PDF invoice is not an e-invoice; the most widespread formats in Germany are XRechnung and ZUGFeRD.
- Cleanse master data, clarify GoBD-compliant archiving and test the exchange with key partners before the deadline.
Contents
Since 1 January 2025, all domestic businesses in Germany have had to be able to receive e-invoices in B2B transactions. The next stage follows on 1 January 2027: companies with prior-year turnover above €800,000 will then also have to issue them. Preparing processes, master data and systems now keeps the changeover from becoming a bottleneck in the middle of day-to-day business.
01The deadlines at a glance
- Since 1 January 2025: all domestic B2B businesses must be able to receive e-invoices.
- Until the end of 2026: paper and PDF invoices may still be sent – PDF only with the recipient’s consent.
- From 1 January 2027: companies with prior-year turnover above €800,000 must issue e-invoices.
- From 1 January 2028: the obligation to issue applies to all other businesses.
- Small-amount invoices of up to €250 are exempt.
Note
This guide is not tax advice. Please confirm binding details on deadlines, exemptions and transitional rules with your tax adviser and against the current guidance of the German Federal Ministry of Finance (BMF).
02What counts as an e-invoice
An e-invoice is an invoice in a structured electronic format based on the European standard EN 16931. Two formats are particularly common in Germany:
a pure XML format. It only becomes readable for people when it is rendered in the system or in a viewer.
a hybrid format combining a PDF with an embedded XML file. The PDF is for viewing; the XML data is for automated processing.
One point that matters in practice: a plain PDF invoice is not an e-invoice – even if it arrives by email. For outgoing invoices, this means that adjusting the layout is not enough – the invoice data has to be generated from the system in structured form.
03Checklist: incoming invoices
Receiving e-invoices has been mandatory since 2025. In many accounting teams, however, they still land in a general inbox and are handled like PDFs. Now is the right time to set up the incoming process properly:
- Define the incoming channels: a central mailbox, a portal or a direct connection to the ERP.
- Check whether your system can read, display and process XRechnung and ZUGFeRD.
- Adapt the approval workflow – for example in SAP VIM or a comparable solution – so that structured data is not keyed in again by hand.
- Set rules for invoices that do not meet the format: who checks them, and who requests a new one?
- Tell suppliers which channel you prefer for receiving invoices.
Practical tip
Do not treat e-invoices like PDFs: adapt the approval workflow so that structured data is not re-keyed by hand.
04Checklist: outgoing invoices from 2027
There is time to prepare for issuing until the end of 2026 – but not unlimited time. Especially where several entities, invoice types or billing systems are involved, planning should start now:
- Establish when the obligation to issue e-invoices applies to your company.
- Agree with IT and your ERP provider which format will be generated and how invoices will be sent.
- Complete customer master data: receiving addresses, customer references and preferred formats.
- Include credit notes, partial and final invoices and other special cases in your planning.
- Review invoice templates and mandatory details together with your tax adviser.
05Master data, archiving, testing and the team
Supplier and customer master data is the foundation of any automated processing. Duplicates, outdated addresses and missing tax details should be resolved before the changeover.
E-invoices must be retained in line with the GoBD, the German rules on electronic bookkeeping and record-keeping. Work out with your tax adviser and IT how the structured data – not just a rendered view – will be archived in an unalterable form.
Test the exchange with your largest suppliers and customers before the deadline – with real invoices rather than samples alone.
The team needs to know what e-invoices look like, where they arrive and what to do when something goes wrong. Short work instructions help more than long manuals. Involve purchasing and sales too, as they are in regular contact with suppliers and customers.
06In practice
At KHD Humboldt Wedag, Loretta Schneiders took over accounts payable with a nine-figure annual volume, worked as key user and tester on the SAP S/4HANA rollout in the payables process and digitalised invoice approval with SAP VIM. These are exactly the workflows on which e-invoice processing builds: master data, approval routes and testing decide whether the changeover holds up in day-to-day business.
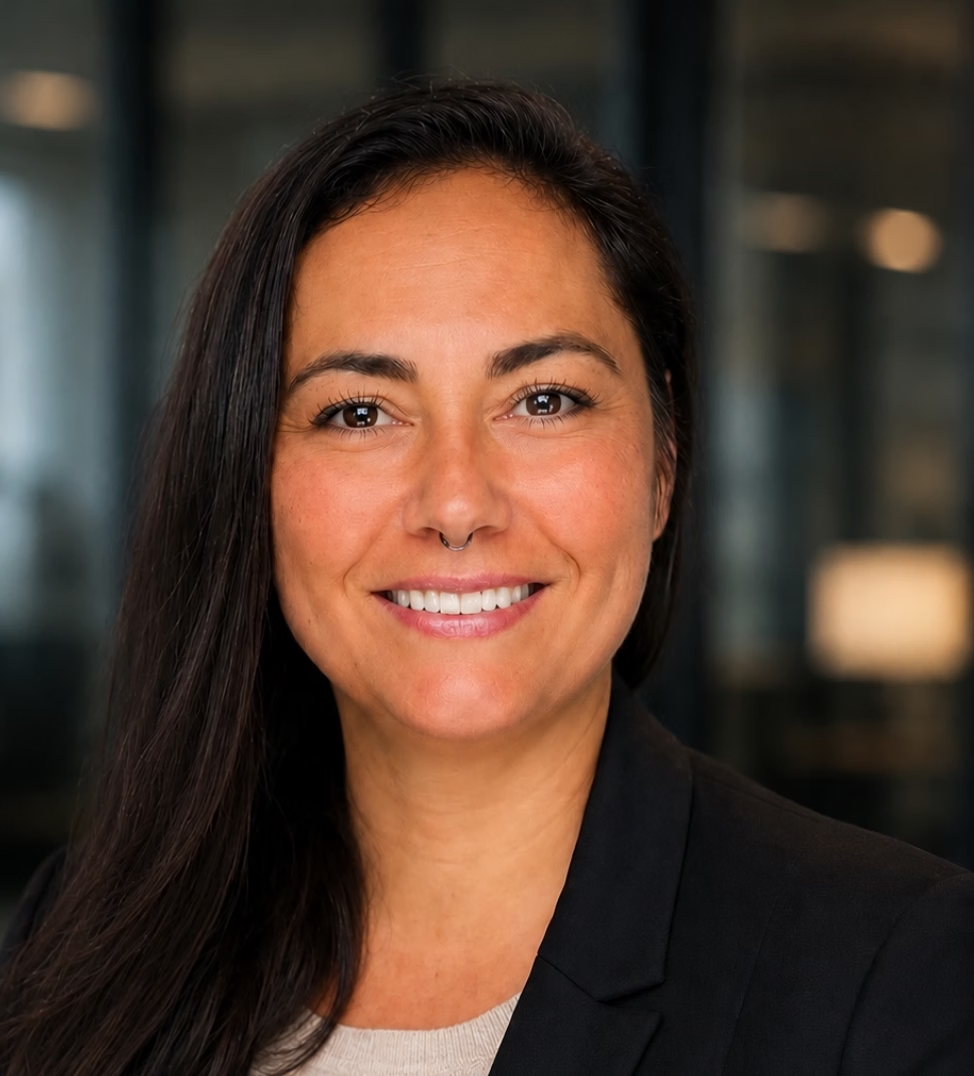
Loretta Schneiders
Senior interim finance leadership with an international outlook. Clarity in numbers. Structure in processes. Leadership with impact.